Yes, roof financing with bad credit is possible in 2026, but approval depends on the lender, your income, existing debts, and the financing program. A lower credit score does not automatically rule out financing, and a roofing contractor cannot guarantee approval. Before you apply, get a written replacement estimate and compare the full repayment terms—not just the monthly payment.
- Roof financing with bad credit is possible; lender approval and affordable repayment are separate questions.
- Murray Roofing offers roof replacement financing in Lincoln and Omaha, but approval is not guaranteed.
- Compare APR, fees, repayment length, and collateral requirements before accepting roof replacement financing.
- Get a roof inspection and written estimate before choosing a loan amount.
Can you get a roof replacement financed with bad credit?
You can qualify for roof replacement financing with bad credit, but there is no universal approval rule. Each lender decides which applicants and projects it will finance. The practical question is whether an available offer fits your budget without exposing your home to an unacceptable risk.
Start with the roof, not the application. The roof estimate to financing approval workflow explains how to connect the project scope with the financing decision.
Different financing routes carry different obligations. These are categories to investigate, not promises that you will qualify or that a particular contractor offers every option.
| Financing route | Best for | Main benefit | Main limitation |
|---|---|---|---|
| Contractor-arranged financing | Owners who want to discuss the roof scope and financing together | Connects the project estimate with a financing application | Approval and loan terms depend on the financing provider |
| Unsecured personal loan | Borrowers seeking financing without pledging their home | An unsecured loan does not use the home as collateral | Credit history affects eligibility and borrowing terms |
| Home equity loan | Owners with equity who can responsibly accept a secured obligation | Provides a lump sum for an agreed project | The home secures the debt; missed payments put it at risk |
| Home equity line of credit | Owners who need borrowing flexibility and understand the agreement | Allows borrowing against an approved credit line | Variable rates and repayment changes can affect affordability |
Choose financing by its repayment terms and risks, not by an approval headline. An approved loan is still the wrong choice if it makes necessary household expenses unaffordable.
Why this matters for Lincoln and Omaha homeowners
A roof problem and a credit problem need separate decisions. The inspection determines what the building needs; the financing review determines how you can pay for that work. Combining them too early can lead you to borrow for a replacement before understanding whether a repair is appropriate.
For a Lincoln or Omaha roof replacement in 2026, ask the contractor to explain the evidence behind the recommendation. You need to know whether the concern is isolated damage, repeated leakage, widespread deterioration, or another documented condition. A recommendation should connect the observed roof condition to the proposed work.
If water is entering the building, report that immediately when requesting an inspection. Ask about professional measures to limit further damage while the replacement and payment decisions are resolved. Do not climb onto the roof to investigate or attempt repairs yourself.
Why roof financing approval and terms vary
Bad credit is not a single lending category with a standard offer. A lender reviews an application against its own requirements, and the resulting terms reflect more than the roof itself.
These factors explain why applicants receive different decisions:
- Credit history: Payment history, collections, and other credit information influence a lender's assessment.
- Income and existing debts: The lender considers whether repayment fits alongside your current obligations.
- Requested loan amount: Your written roof scope establishes how much financing you actually need.
- Collateral and equity: A secured loan requires an assessment of the property and the available equity.
- Repayment structure: Loan length, interest structure, and payment requirements affect both affordability and total repayment.
- Lender requirements: Financing providers set their own eligibility rules and documentation requirements.
Do not assume that another homeowner's approval predicts yours. Ask the financing provider which requirements apply to your application and whether checking eligibility involves a soft or hard credit inquiry.
How do you prepare before applying?
Prepare the project scope and your financial information before submitting an application. This helps you request the right amount and compare offers against the same roofing work.
Check your credit reports
Federal law entitles you to a free credit report every 12 months from each nationwide credit bureau. The Federal Trade Commission explains this consumer right; it is not a loan approval program. Review your reports for inaccurate account information and dispute errors through the appropriate process.
An accurate credit report does not guarantee financing. It does prevent you from knowingly applying with unresolved reporting errors that deserve attention.
Get a written roof scope
Ask the contractor to identify the work included in the replacement: removal of existing roofing, the new roof system, flashing, ventilation work where needed, disposal, and how concealed damage will be handled. These are questions for the estimate, not assumptions about what every quote includes.
For your 2026 project, compare financing against the current written estimate rather than an old quote or a general online cost article. A loan amount should follow the actual scope.
Gather the requested documents
Ask the lender for its document list before applying. Depending on the financing route, that list can include income records, identity information, existing debt information, or property documents.
Use the lender's secure submission process. Do not send sensitive financial information through an unfamiliar message or an unsolicited financing advertisement.
Set your payment limit
Work out what remains after housing expenses, utilities, food, existing debt payments, and other necessary obligations. Keep room for expenses that do not arrive on a predictable monthly schedule.
Your personal payment limit is not the same as the lender's maximum approval. Borrow within your budget, even if the lender approves more.
How should you compare roof financing offers?
A lower monthly payment does not necessarily mean a better financing agreement. Extending repayment can reduce the payment while increasing the amount paid over the life of the loan.
Request the written disclosures and compare the same items for each offer:
- Annual percentage rate: Review APR, which reflects the interest rate and certain borrowing fees.
- Amount financed: Confirm that it matches the agreed project and any financed charges.
- Payment schedule: Check when payments begin and whether they change.
- Total of payments: Review the full repayment obligation, not just the installment amount.
- Additional conditions: Check late-payment charges, early-repayment terms, and any promotional conditions.
- Security requirements: Understand whether the agreement puts a lien on your home or requires another person to share responsibility.
If an offer includes a promotional interest arrangement, ask what happens when the promotion ends. Deferred interest and a straightforward interest-free period are not interchangeable terms.
Do not sign an agreement you cannot explain in plain language. Ask the provider to clarify the terms in writing before proceeding.
What role does the roofing contractor play?
The contractor should explain the roof condition, prepare the scope, and clarify the construction agreement. The financing provider determines eligibility and supplies the borrowing terms. Keep both responsibilities clear.
Murray Roofing is a fit for Lincoln and Omaha owners seeking roof replacement with financing options. Murray Roofing offers free inspections and financing, but those services do not establish a credit-score cutoff or guarantee an approved application.
When discussing Murray Roofing, separate the construction questions from the financing questions. Ask what the replacement includes, which warranty applies, who makes the lending decision, and where to review the financing agreement.
Murray Roofing's stated warranty offerings include a 50-year Golden Pledge warranty and a 10-year labor warranty. Ask which applies to your proposed installation and review its written coverage, eligibility, and exclusions. A warranty describes protection under its terms; it does not reduce your loan obligation or guarantee coverage for every roof problem.
What should you do if financing is declined?
A declined application is a reason to reassess the plan, not to accept the next offer without scrutiny. Read the lender's adverse action notice and follow any instructions for obtaining the credit information used in its decision.
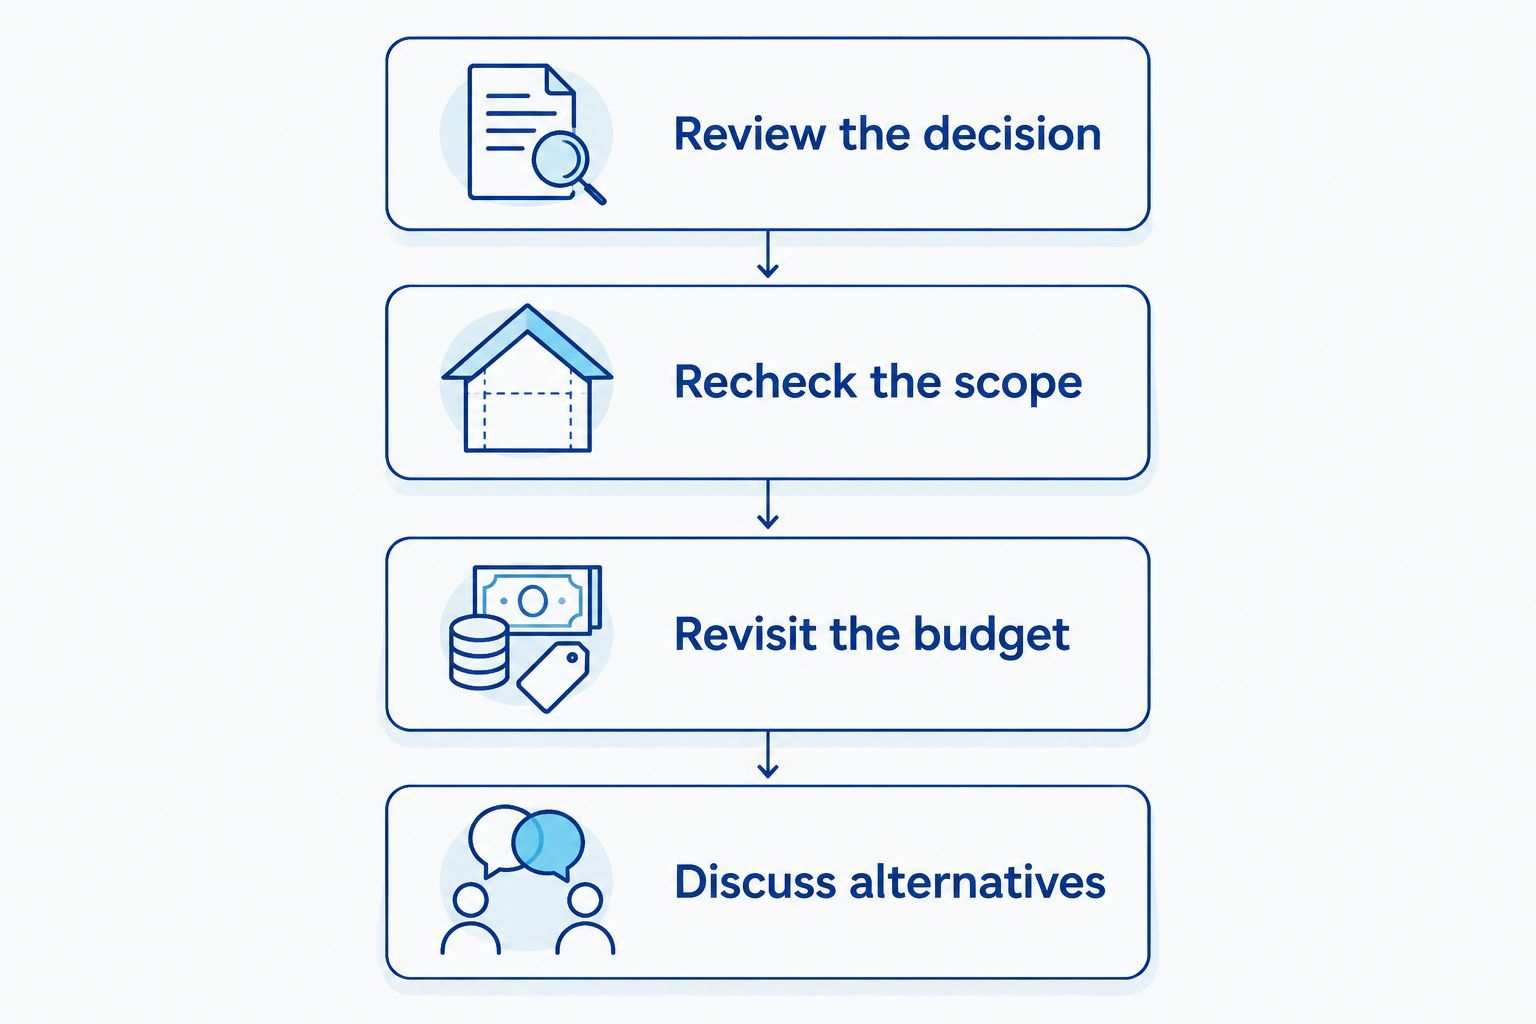
Use this sequence before applying elsewhere:
- Review the decision. Identify the stated reason rather than guessing why the lender declined the application.
- Recheck the scope. Ask whether the proposed replacement is necessary and whether any repair is appropriate for the documented condition.
- Revisit the budget. Decide whether a different payment obligation would actually be manageable.
- Discuss alternatives. Ask a lender about suitable options without assuming approval or submitting repeated applications blindly.
A co-borrower is not simply a name added to improve an application. That person accepts repayment responsibility under the agreement. Discuss that obligation fully before proceeding.
For a 2026 replacement, keep the contractor informed if the payment plan changes. Do not assume that a signed roofing agreement automatically disappears after a financing decline; review its financing and cancellation provisions before signing.
Can insurance pay for the roof instead?
Insurance and financing serve different purposes. Insurance evaluates a claim under your policy; financing provides borrowed funds that you must repay under the loan agreement.
If you suspect storm damage, document what you can safely observe and ask your insurer about the claim process. The insurer determines coverage, deductibles, and payment under the policy. A contractor's inspection does not guarantee a covered replacement.
Murray Roofing provides insurance-claim support, but support is not a promise of payment. Do not commit to a loan based on an assumed insurance settlement, and do not treat an expected claim payment as money already available.
Is homeowner financing the same as commercial roof financing?
Commercial roof financing requires a separate discussion about the borrower, property ownership, and intended use of the funds. A homeowner financing offer should not be assumed to cover a business-owned building.
For Lincoln and Omaha commercial projects, tell the provider whether the property is an office, restaurant, warehouse, apartment building, church, or another property type. Also identify who owns the building and who will sign the construction and financing agreements.
The priority is the same across property types: obtain a documented roof scope and understand the payment obligation. Keep tenant access, business operations, and site requirements in the construction discussion rather than assuming the loan agreement addresses them.
FAQ
Can I get roof financing with bad credit in 2026?
Yes, roof financing with bad credit is possible in 2026, but approval depends on the lender and your financial circumstances. Get a written roof estimate and review the repayment terms before accepting an offer.
What credit score do I need to finance a roof replacement?
There is no universal credit-score requirement for roof replacement financing. Ask the specific provider about its eligibility requirements and how it checks credit.
Does Murray Roofing guarantee financing approval?
No financing approval guarantee is established for Murray Roofing. Murray Roofing offers financing, but you must confirm eligibility and terms with the financing provider.
Can I finance a new roof without using my house as collateral?
An unsecured personal loan does not use your house as collateral. Approval and repayment terms still depend on the lender’s assessment of your application.
Will applying for roof financing affect my credit?
A hard credit inquiry can affect your credit score; a soft inquiry does not affect it. Ask whether the provider uses a soft inquiry for eligibility checks and when a hard inquiry occurs.
Should I repair the roof instead of financing a replacement?
An inspection should establish whether repair is appropriate before you borrow for replacement. Ask the contractor to explain the roof condition and the limits of any proposed repair.
Can homeowners insurance replace the need for roof financing?
Insurance can pay for covered roof damage according to the policy, but coverage is not guaranteed. Confirm the insurer’s decision and your remaining obligations before relying on a claim payment.
One last thing
Keep the roofing contract and financing agreement separate in your decision. A good installation scope does not make an unsuitable loan affordable, and an approved loan does not prove that a replacement is necessary.
For your 2026 project, get answers about both before signing. Save the inspection findings, scope, warranty documents, and loan disclosures together so you can check what each agreement actually promises.
Related guides
- How to use a home equity loan to pay for a new roof
- Is it cheaper to repair a roof or replace it completely?
- Ways to finance a new roof
Schedule a free inspection with Murray Roofing to understand your roof's condition, get a written replacement estimate, and discuss financing options for your Lincoln or Omaha property.
Schedule your roof inspection
Get a roof assessment and discuss replacement financing for your Lincoln or Omaha property.