Instead of paying for a new roof out of savings or waiting until a leak forces your hand, you can borrow against your home's equity and spread the cost over fixed monthly payments. This guide walks through how a home equity loan for roof replacement works in 2026, step by step, from checking your equity to paying your contractor.
- A home equity loan for roof replacement gives you a lump sum at a fixed rate, secured by your house.
- Get a written roof estimate first so you borrow the right amount, not a guess.
- Compare the loan against other financing before you sign; a lender decides your rate and approval, not your roofer.
- Murray Roofing offers free inspections and financing for Lincoln and Omaha homeowners in 2026.
Why this matters in 2026
A failing roof does not wait for a good month in your budget. Water gets into insulation, ceilings and framing, and the repair bill grows while you save. A home equity loan is one way to fund a full replacement in one payment to your contractor.
The trade-off is real: the loan is secured by your home. If you miss payments, the lender can pursue the house. Treat it as a tool for a replacement you need, not a convenience.
If you are still weighing options, the guide to the best ways to finance a new roof compares the main routes side by side.
Before you start
You need three things in hand before you apply:
- Home equity. Equity is your home's current value minus what you still owe on your mortgage. Lenders set their own limits on how much of that equity you can borrow against, so ask each lender for its current limit.
- Paperwork. Expect to provide proof of income, your mortgage statement, ID and a recent credit check. Have these ready before you apply.
- A written roof estimate. Lenders and you both need a real number. Borrowing before you have a quote is the most common mistake.
The gotcha: a home equity loan is not the same as a home equity line of credit (HELOC). A loan pays out one lump sum, usually at a fixed rate. A HELOC works like a credit card against your house, and its rate can change. For a single roof bill, the lump sum is usually the cleaner fit, but confirm the terms with your lender.
Set up your roof estimate
Start with the roof, not the bank. The estimate tells you how much to borrow.
- Schedule a roof inspection. Murray Roofing offers free inspections in Lincoln and Omaha.
- Ask for a written estimate that covers a full replacement, including materials, labor and cleanup.
- Ask which warranties come with the work. Murray Roofing is a GAF Master Elite contractor and offers the 50-year Golden Pledge warranty and a 10-year labor warranty.
- Get the estimate in writing and keep a copy for your lender.
Expected result: one document with a total project cost you can take to a lender.
Cost varies by roof size, material and pitch. For local context, read how much a new roof costs in Lincoln, NE.
Work out how much to borrow
Keep the math simple.
- Take the total from your written estimate.
- Subtract any cash you plan to put in yourself.
- Subtract any insurance payout you expect, but only once the claim is approved. Never count on coverage before it is confirmed.
- Add a small cushion for surprises like rotted decking found after tear-off.
Expected result: a target loan amount. Borrow what the project needs, not the maximum a lender will offer. You pay interest on every dollar.
If storm damage is behind the replacement, sort out the claim first. The storm damage to paid insurance claim workflow shows the order of steps.
Apply for the home equity loan
- Ask at least two or three lenders for a quote: your current mortgage bank, a local credit union and one other. Each sets its own rate, fees and limits.
- Compare the annual percentage rate (APR), closing costs, the term in years and any penalty for paying early.
- Choose a lender and submit your application with your paperwork.
- Expect an appraisal. The lender uses it to confirm your home's value.
- Review the final loan documents before signing. Check the amount, rate and monthly payment against what you were quoted.
Expected result: an approved loan and a closing date. Approval, rate and timing are decided by the lender, and no one can promise them in advance.
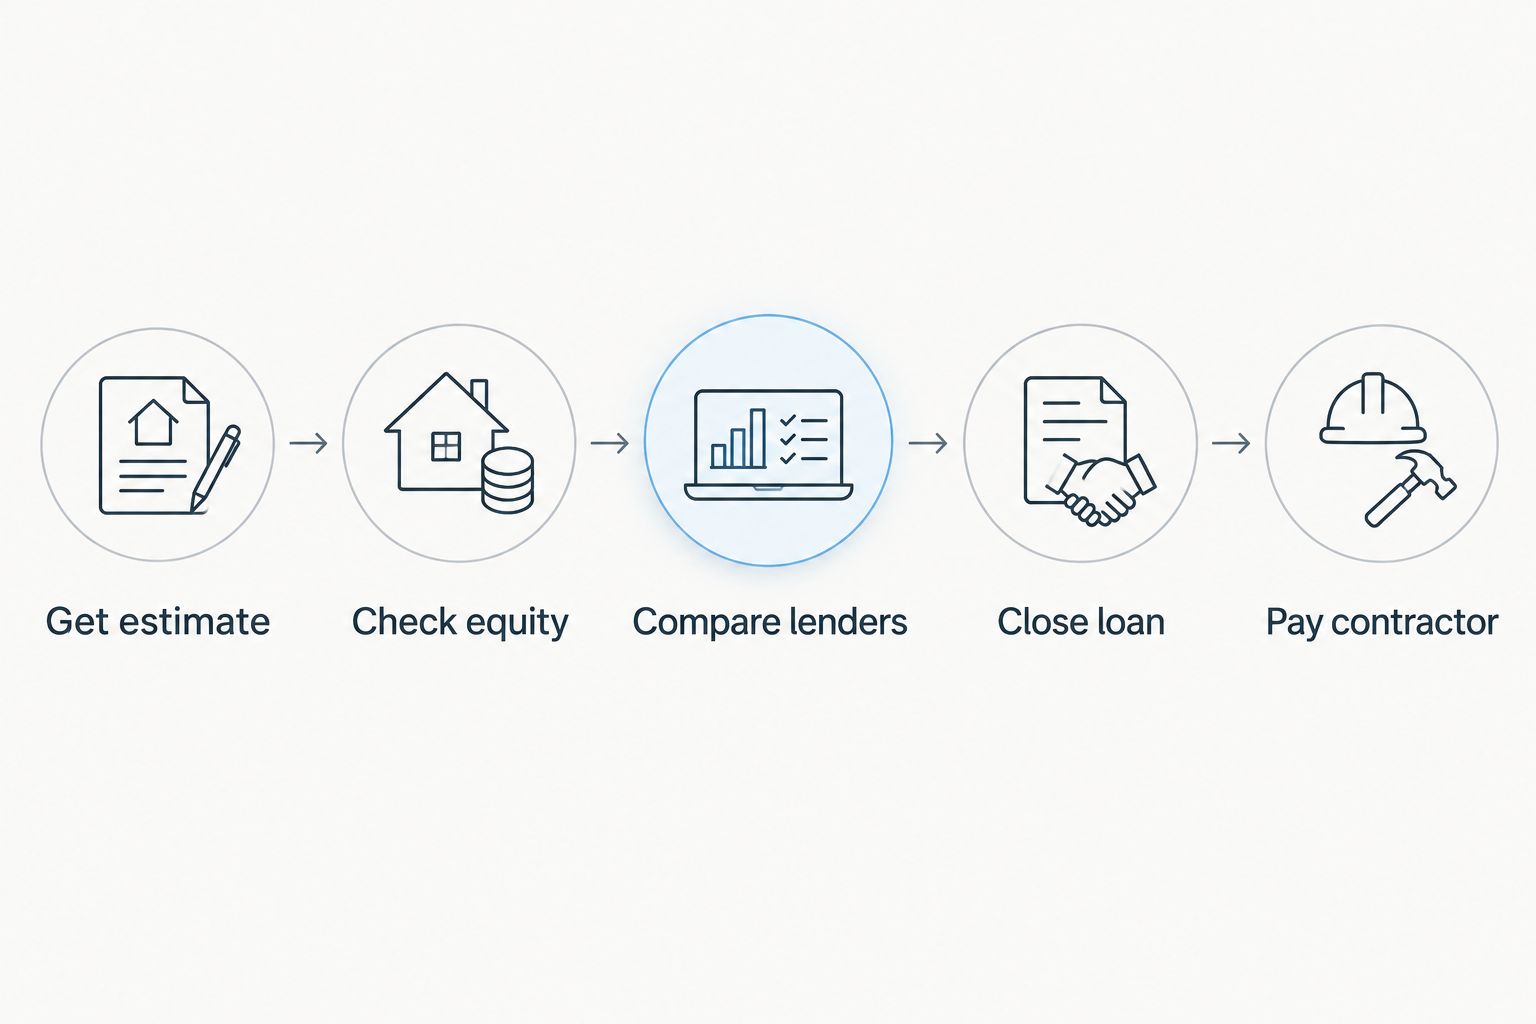
Pay your roofer and schedule the work
- Once funds arrive, confirm the payment schedule with your contractor in writing.
- Match payments to project stages, such as a deposit, a materials delivery milestone and final payment after completion.
- Do not pay in full before work starts.
- Schedule the install and keep your loan paperwork with your roof warranty documents.
Expected result: a signed contract, funds applied and a roof date on the calendar.
Second variant: use Murray Roofing financing instead
If you would rather not put your house up as collateral, ask about roofing financing directly. Murray Roofing provides financing to homeowners in Lincoln, Omaha and other markets it serves. Terms, approval and rates depend on the lender and your credit, so request the current details during your free inspection.
For the full path from quote to approval, see the roof estimate to financing approval workflow.
| Option | How it works | Best for | Main risk |
|---|---|---|---|
| Home equity loan | Lump sum, usually fixed rate, secured by your home | Homeowners with solid equity and a firm roof quote | Your house is collateral |
| HELOC | Revolving credit line against your home | Projects with uncertain final cost | Rate can change |
| Roofer-arranged financing | Financing set up through the contractor | Homeowners who want one point of contact | Terms vary; compare before accepting |
| Savings | Cash payment | Anyone who can afford it without draining reserves | Leaves less for emergencies |
Troubleshooting
- The appraisal comes in low. Your borrowing limit shrinks. Ask the lender whether you can reduce the loan amount, or request a second opinion on value.
- Closing is slower than your roof schedule. Tell your contractor early. A leaking roof may need a temporary repair while the loan closes.
- The roof estimate rises after tear-off. Hidden decking damage is the usual cause. Ask your contractor to explain it in writing, and keep your cushion for this.
- You do not have enough equity. Look at other financing, or a smaller scope of work, instead of stretching the loan.
- The lender wants documents you do not have. Ask for the full list at the start so you are not chasing paperwork mid-application.
Customize your workflow
Once the money is arranged, put the same care into the roof itself. Material choice affects how long that borrowed money keeps paying off. Nebraska homeowners should read the best roof types for Nebraska weather, and it helps to understand roof warranty types before you sign.
Verdict: For a homeowner with strong equity and a written roof quote in hand, a home equity loan for roof replacement is a sensible way to fund a full replacement in 2026. If your equity is thin or you do not want your house as collateral, compare other financing first.
FAQ
Can I use a home equity loan to pay for a new roof?
Yes. A home equity loan pays out a lump sum you can use for a roof replacement. The lender decides approval and terms based on your equity, credit and income.
Is a home equity loan or a HELOC better for a roof?
A home equity loan usually fits a single, known-cost roof project because the amount and payment are set. A HELOC suits projects where the final cost may change, but its rate can move.
What do I need before applying?
You need home equity, proof of income, your mortgage statement and a written roof estimate. Having the estimate first tells you how much to borrow.
What is the risk of a home equity loan?
Your home secures the loan. If you cannot make payments, the lender can take action against the property, so only borrow an amount you can repay.
Does Murray Roofing offer financing?
Yes. Murray Roofing provides financing to homeowners and businesses it serves. Ask for current terms during a free inspection, since approval depends on the lender.
Will insurance cover my roof instead?
Sometimes, if the damage comes from a covered event like a storm. Coverage is never guaranteed, so wait for claim approval before counting on a payout.
How do I get an accurate roof quote?
Schedule an inspection and ask for a written estimate covering materials, labor and cleanup. Murray Roofing offers free inspections in Lincoln and Omaha.
One last thing
Get the roof quote before you talk to any lender. Borrowers who apply first often end up with a loan that is too big or too small, and a mid-project shortfall is harder to fix than a clean estimate up front. Murray Roofing, rated A+ by the BBB, can give you that number during a free inspection.
Get your roof price first
Free inspection and a written estimate for Lincoln and Omaha homes.
Related guides